What is the market overview and industry significance of the Sanitized Tote Certification Programs Market?
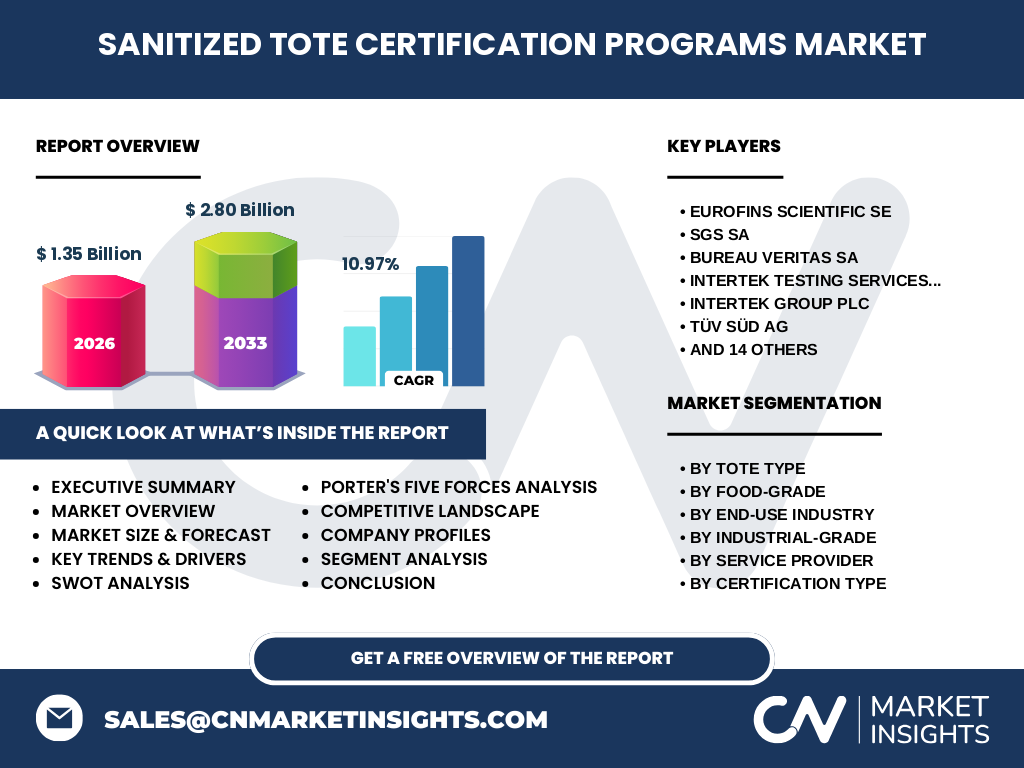
Our analysis indicates that the Sanitized Tote Certification Programs Market valued at 1.35 Billion in 2026 plays a critical role in global supply chain integrity. These programs validate intermediate bulk containers for safe transport across food, pharma, and chemical sectors, ensuring strict adherence to microbiological and chemical hygiene standards.
Structural Growth Drivers and Market Restraints in the Sanitized Tote Certification Programs Market
The market is propelled by stringent FDA and EU food safety mandates, alongside soaring demand for reusable packaging. However, high recertification downtime and complex cross-border regulatory fragmentation act as significant operational restraints for logistics providers operating across major European and North American trade corridors.
Emerging industry trends and evolving growth patterns
The shift toward automated cleaning validation and IoT-enabled cleanliness tracking is redefining industry standards. Digital audit trails now allow real-time verification of tote sterility, directly favoring testing providers equipped with advanced molecular detection technologies and cloud-based compliance dashboards.
How did the COVID-19 pandemic impact the Sanitized Tote Certification Programs Market trajectory?
The pandemic drastically accelerated baseline hygiene protocols across cold-chain logistics. Microbiological testing certification surged in priority as pharmaceutical distribution and food supply resilience became paramount, setting a permanently elevated baseline for post-pandemic recovery and sanitization stringency.
Competitive benchmarking and strategic dynamics among market leaders
Market concentration remains moderate to high, anchored by multinational testing giants. Firms like Eurofins Scientific SE, SGS SA, and Bureau Veritas SA leverage global laboratory networks to offer end-to-end audit solutions, outcompeting regional players through unmatched accreditation scope and cross-border regulatory expertise.
Executive summary of key findings in the Sanitized Tote Certification Programs Market
Our research projects the market to expand from 1.35 Billion in 2026 to reach 2.80 Billion by 2033 at a robust CAGR of 10.97%. This expansion is driven by escalating biosecurity protocols and rigorous end-user demands for contamination-free intermediate bulk transport.
Market forecast trajectory from 2027 to 2033
Driven by compounding industrial compliance needs, the market will achieve a rapid expansion trajectory, scaling from its 2026 baseline to 2.80 Billion by 2033. This consistent growth reflects a stellar 10.97% CAGR fueled by pharmaceutical cold-chain investments.
Comprehensive segmentation analysis of the Sanitized Tote Certification Programs Market
Segmentation spans across Tote Types (plastic, metal, composite, specialized), Food-Grade and Industrial-Grade certifications, and distinct End-Use Industries ranging from chemicals to cosmetics. Pharmaceutical-Grade certifications represent the highest-margin segment due to strict sterility assurance requirements.
Geographic distribution and regional performance dynamics
North America and Europe currently dominate market consumption due to rigorous OSHA, FDA, and EMA guidelines. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, propelled by expanding chemical manufacturing hubs in China and stringent export packaging mandates in India.
In-depth regional review of key high-growth territories
European markets prioritize environmental compliance and chemical containment certifications, heavily involving entities like TÜV SÜD AG and TÜV Rheinland AG. Conversely, North American operations focus extensively on Good Manufacturing Practice certification and food-contact material safety standards administered by agencies like NSF International.
Strategic positioning of leading companies in the industry
Industry leaders like Intertek Group plc, UL Solutions Inc., and Element Materials Technology Group maintain competitive moats through specialized durability testing and customized compliance frameworks. Their strategic positioning centers on integrating physical material stress testing with rapid microbiological audit validations.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers is moderate due to the specialized nature of pharmaceutical and food-grade standards, while threat of substitutes remains low. High capital requirements for accredited testing labs create a substantial barrier to entry, protecting incumbent certification providers.
SWOT analysis highlighting internal capabilities and market threats
Strengths include robust global laboratory footprints and recognized accreditations. Weaknesses involve high operational setup costs. Opportunities lie in emerging biotech logistics, whereas threats stem from evolving, unpredictable international trade compliance mandates and localized regulatory shifts.
Value chain analysis from raw material testing to end-user deployment
The value chain flows from raw polymer and metal alloy testing, through intermediate tote manufacturing, to third-party cleaning validation and final deployment in food or biotech facilities. Third-party certifiers capture significant value by guaranteeing regulatory compliance at critical logistics junctions.
Strategic investment insights and high-potential areas
Investors should target acquisitions of regional laboratories specializing in cleanroom compliance certification and IoT-enabled sensor validation. Capitalizing on automated cleaning validation certification platforms offers superior long-term yield given the ongoing shift toward digital supply chain transparency.
Conclusion and critical takeaways for industry stakeholders
Reaching 2.80 Billion by 2033 at a 10.97% CAGR underscores the sector's essential nature. Stakeholders must embrace digital audit technologies and expand pharmaceutical-grade service offerings to capture premium margins in an increasingly rigorous global regulatory environment.
Research methodology for baseline estimates and data triangulation
Our baseline figures are meticulously triangulated by combining trade registry data, primary executive interviews with quality assurance heads at companies like DNV Group AS and BSI Group, and secondary macroeconomic indicators from global packaging and chemical industry associations.
Scope of the report, coverage parameters, and analytical limitations
This report covers global certification program revenues from 2026 to 2033 across specified tote and grade categories. Limitations include unforeseen macroeconomic trade policy shifts and variable enforcement timelines of regional sanitization mandates across developing industrial economies.
Recent developments, strategic partnerships, and product launches
Recent market activities feature strategic acquisitions by Mérieux NutriSciences and QIMA Limited to expand digital testing footprints. Concurrently, FoodChain ID Group Inc. has launched enhanced traceability protocols to streamline cross-border food-grade tote sanitation validations.